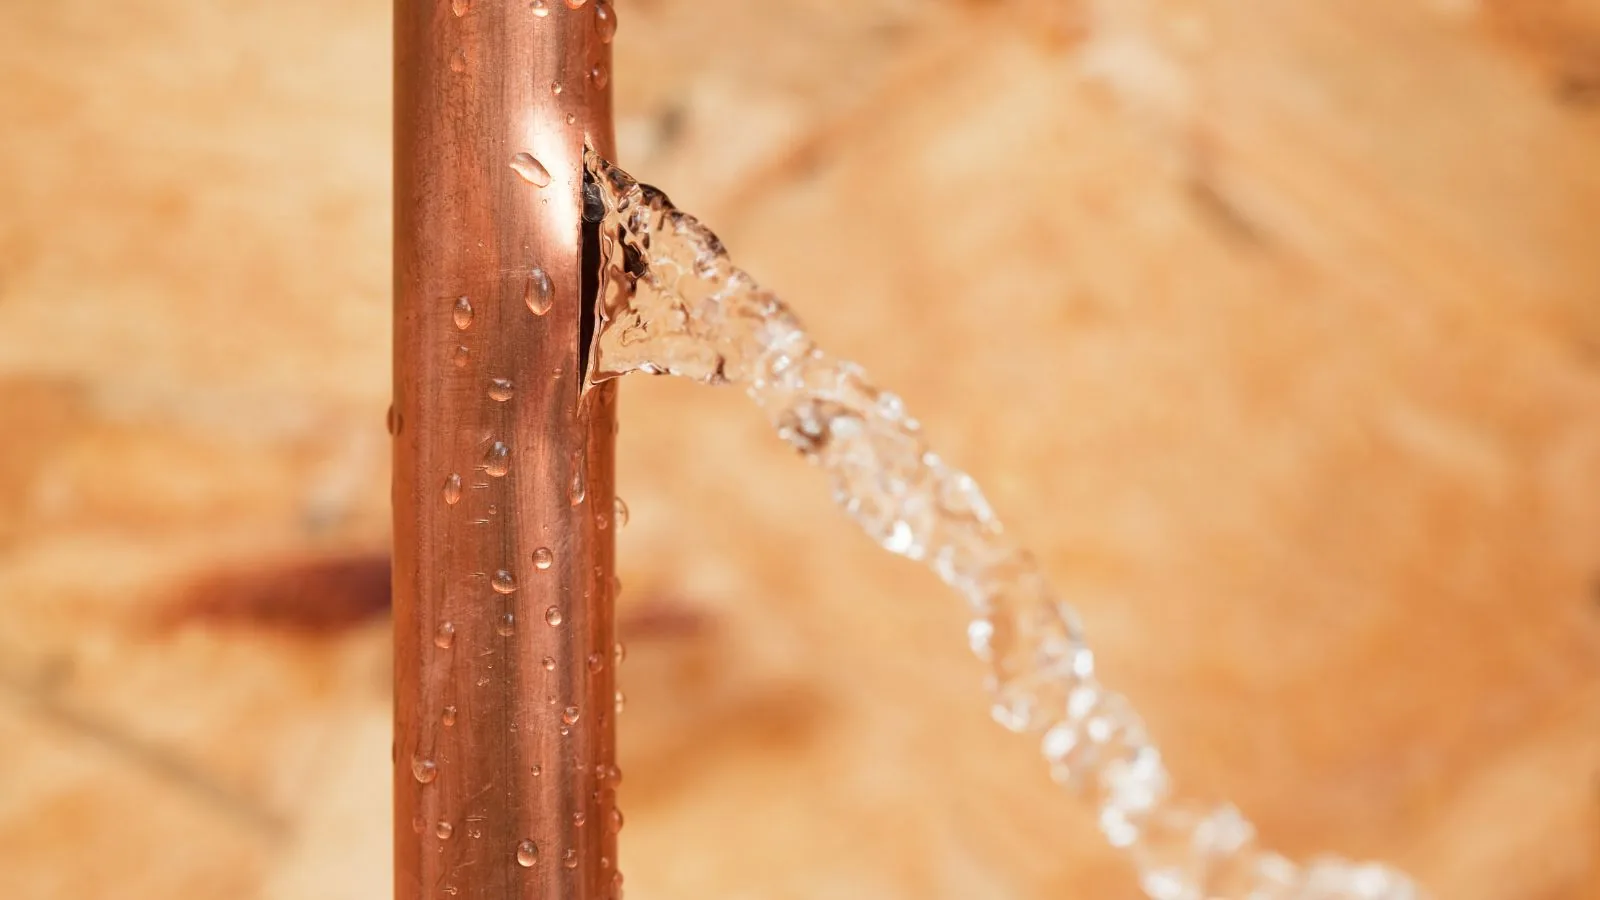
The short answer: it depends on how the water got in
Homeowners policies are written around causes. Most cover damage from a sudden and accidental event, such as a supply line that bursts or an appliance hose that splits. Most do not cover damage that builds slowly over time, such as a leak under a sink that ran for months, or damage from flooding, which is usually excluded.
That one distinction explains most claim outcomes. Two houses can have the same wet floor and receive opposite answers, because one leak was a sudden failure and the other was a slow drip nobody noticed. Your policy wording sets the rule, so read it, or ask your insurer to explain it, before you need it.
This guide is general information, not a coverage opinion. We never promise that a claim will be approved, and we do not name or recommend any insurer.
What sudden and accidental usually means
Sudden means it happened quickly, and accidental means you did not expect or cause it. A pipe that bursts in a wall, a water heater tank that fails, a dishwasher hose that comes off, or a washing machine that overflows all fit that picture.
Policies often cover two things after such an event. One is the damage to your home, such as ceilings, floors and drywall. The other is the cost of drying and cleanup, which is sometimes called mitigation. Many policies also expect you to take reasonable steps to stop more damage, which is one reason to call a crew quickly.
What is often not covered is the failed part itself. The pipe, the water heater or the appliance that broke is commonly considered wear and tear, while the resulting damage may be covered.
Common water damage causes and how they are often treated
This table shows the usual pattern. It is not a promise, because every policy is different.
| Cause | Often covered? | What to check |
|---|---|---|
| Burst pipe or supply line, sudden | Often yes, for resulting damage | Whether the pipe itself is excluded |
| Appliance hose or tank failure, sudden | Often yes, for resulting damage | The appliance itself is usually not covered |
| Slow leak over weeks or months | Often no | Maintenance and long-term seepage exclusions |
| Rain through a storm-damaged roof | Often yes | Windstorm or hail deductible rules |
| River or surface flooding | Usually no under homeowners | Separate flood policy |
| Sewer or drain backup | Often excluded unless endorsed | A water backup endorsement |
| Mold after a covered loss | Sometimes, with limits | Mold sublimits and exclusions |
Flood and sewer backup: the two big exclusions
A standard homeowners policy typically excludes flood, meaning surface water or rising water from outside. That means a river overflow, heavy runoff entering a basement window, or water pushed up through the ground may need flood coverage, which is sold separately through the National Flood Insurance Program or private insurers.
Sewer and drain backup is a separate gap. Many policies exclude it unless you added a water backup endorsement. If you are not sure whether you have one, look for it on your declarations page or ask your agent. Our pages on flood damage restoration and sewage backup cleanup explain how those losses are handled.
If you are unsure whether a loss counts as a flood or a sudden pipe failure, say what happened in plain words and let the insurer decide. Do not label it yourself in a way that closes the door.
Water in the house? Do the first steps now
Stop the source and call our 24/7 line. Coverage questions can follow.
Questions worth asking your insurer today
Ask these before a loss, when nobody is stressed. Write down the answers:
- What counts as sudden and accidental under my policy?
- Is damage from a slow leak excluded, and how long is too long?
- Do I have flood coverage, and does my lender require it?
- Do I have a water backup endorsement for sewers and sump pumps?
- What are my deductibles, and do any apply only to certain causes?
- Is there a limit on mold, and what is it?
- Does the policy pay for drying and cleanup separately from repairs?
Small claims, deductibles and your record
Many homeowners hesitate to file a small claim, because a claim can affect future premiums or renewal. That is a real consideration. A deductible may also exceed the cost of a small repair. Ask your agent how claims are counted and what happens if you ask a question without filing.
Whatever you decide, document the damage. Photograph the water, the source and the affected areas. Keep receipts for emergency repairs. If you later decide to file, your records are ready, and if you decide not to, you still have a clear account of what happened.
Dumont note: where to check flood and storm exposure
Dumont is a Bergen County borough of 1.95 square miles with 6,572 housing units in the 2020 Census. Every address has a mapped flood status on the FEMA Flood Map Service Center, which shows whether your property is in a Special Flood Hazard Area. Look yours up, since flood coverage is the gap most likely to surprise a homeowner.
The U.S. Geological Survey's summary of the April 2007 floods in New Jersey records rainfall of more than 9 inches at gauges in Bergen County and peak river levels on the Hackensack River that were records at the time. Dumont borders New Milford, which sits on that river. The practical point is that storms in this area can produce flooding that a standard homeowners policy does not cover, so confirm your flood coverage before the next big storm.
For questions about how a policy is interpreted, the New Jersey Department of Banking and Insurance publishes consumer guidance, and your agent can explain your own wording. Our pages for New Milford, which sits on the river, and Oradell, which has the reservoir, describe the local water features in more detail.
Frequently asked questions
Often the resulting damage is covered when the burst was sudden and accidental, while the pipe itself may not be. Check your policy or ask your insurer.
Often not. Many policies exclude damage that builds up over time, so fix leaks quickly and keep maintenance records.
Usually not. Flood damage typically needs a separate flood policy. Check your policy and the FEMA flood map.
Renters policies usually cover your belongings from sudden water events, while the building is the landlord's responsibility. Check your policy.
Check your address on the FEMA Flood Map Service Center. If it is in a Special Flood Hazard Area and you have a federally backed mortgage, your lender will likely require flood coverage. Even outside it, ask your insurer whether coverage makes sense for your lot.